A country risk assessment shows how conditions in a foreign market may affect a specific business decision. For a mid-market B2B company, it must go beyond a country score. It should lead to one of three choices: run a capped pilot, pause for named proof, or stop when a condition exceeds the agreed exposure ceiling.
Ask a practical question: can this offer reach this buyer through this channel and transaction model? Can it do so within our exposure limit by the decision date? Treat every unknown as unknown until it is tested.
What is a country risk assessment?
The Office of the Comptroller of the Currency links country risk to economic, social, and political conditions and events in a foreign country. Those factors may harm a financial institution's operations (OCC, Country Risk). That definition is a useful starting point for a commercial market-entry decision. The operating question must still be narrower and more concrete.
Go International Advisory treats the assessment as a decision tool. It names the country, offer, buyer, channel, transaction model, exposure ceiling, and decision date. It then separates evidence that is often mixed together. A strong governance indicator cannot compensate for absent customer demand. A promising buyer conversation cannot settle a regulatory question. A respected partner cannot remove payment or currency exposure.
The result is not a prediction. It is a documented choice based on current evidence, stated uncertainty, and a bounded next step.
How does country risk differ from sovereign risk?
Country risk covers the wider economic, social, and political conditions that can affect operations. Sovereign risk is narrower. It asks whether a government may be unable to repay debt. It also covers a government's unwillingness to repay (OCC, Country Risk).
That distinction matters for an operating company. A sovereign rating may contribute to the financial picture, but it does not answer questions such as:
- Can the exact offer be sold through the intended channel?
- Will the named buyer group pay for it?
- Can a partner execute the required work?
- Can the company collect cash and limit currency exposure?
- Can the company exit if the test fails?
A single sovereign rating is therefore not a complete operating-market assessment. It can be evidence in one lane, never the whole decision.
Which evidence lanes should the assessment keep separate?
The framework uses five evidence lanes. Keeping them separate prevents a strong signal in one area from hiding a serious gap in another.
| Lane | Evidence to collect | Warning signal | Next test |
|---|---|---|---|
| Country and governance conditions | Current country-level evidence, named sources, source dates, and direction of change | Evidence is old, conflicting, or treated as a forecast | Refresh the source and record what changed |
| Regulation and market access | Rules and access conditions for the exact offer, buyer, channel, and transaction model | The conclusion relies on a general country guide rather than the named offer | Verify the precise question locally with the appropriate specialist |
| Commercial demand | Evidence that the named buyer has a problem, budget, and willingness to buy | Country growth or sector opportunity is used as a substitute for buyer evidence | Test a defined proposition with the named buyer group |
| Channel and partner execution | Partner role, capability, incentives, ownership, and operating proof | Reputation or introductions replace proof of delivery | Run a limited execution test with named responsibilities |
| Cash, payment, currency, and exit | Payment path, timing, currency exposure, loss ceiling, and exit conditions | Revenue potential is discussed without collection or exit terms | Test the transaction path within a capped exposure |
The World Bank's Worldwide Governance Indicators provide six governance dimensions. They cover Voice and Accountability, Political Stability and Absence of Violence or Terrorism, and Government Effectiveness. They also cover Regulatory Quality, Rule of Law, and Control of Corruption. The indicators combine perceptions from many data sources (World Bank, Worldwide Governance Indicators). They are a country-level lens. They are not a forecast, a customer-demand measure, or a go or no-go score.
The U.S. International Trade Administration's Country Commercial Guides cover market conditions, opportunities, regulations, and business customs in more than 125 countries. U.S. embassies prepare the guides (International Trade Administration, Country Commercial Guides). Use them as a starting source, then verify the named sector, customer, and route locally.
How do you run a country risk assessment step by step?
1. Define the decision
Write one decision statement before collecting evidence. Name the country, offer, buyer, channel, and transaction model. Add the maximum exposure and decision date. If one element is missing, the assessment is too broad to guide action.
2. Open five separate evidence lanes
Collect country and governance evidence. Gather the exact regulatory and access conditions. Then add demand, partner execution, and financial or exit exposure. Do not average them into one early score. Separation makes gaps visible.
3. Create a risk record
For every material risk, record:
- the evidence and its date;
- the direction of the signal;
- confidence in the evidence;
- the consequence for the decision;
- the person who owns the next action;
- the next test;
- the date when the evidence expires.
Keep fact and inference in separate fields. Name the source beside each fact. State who can overturn the decision. Define the evidence that would justify the change.
4. Set the outcome rules before the debate
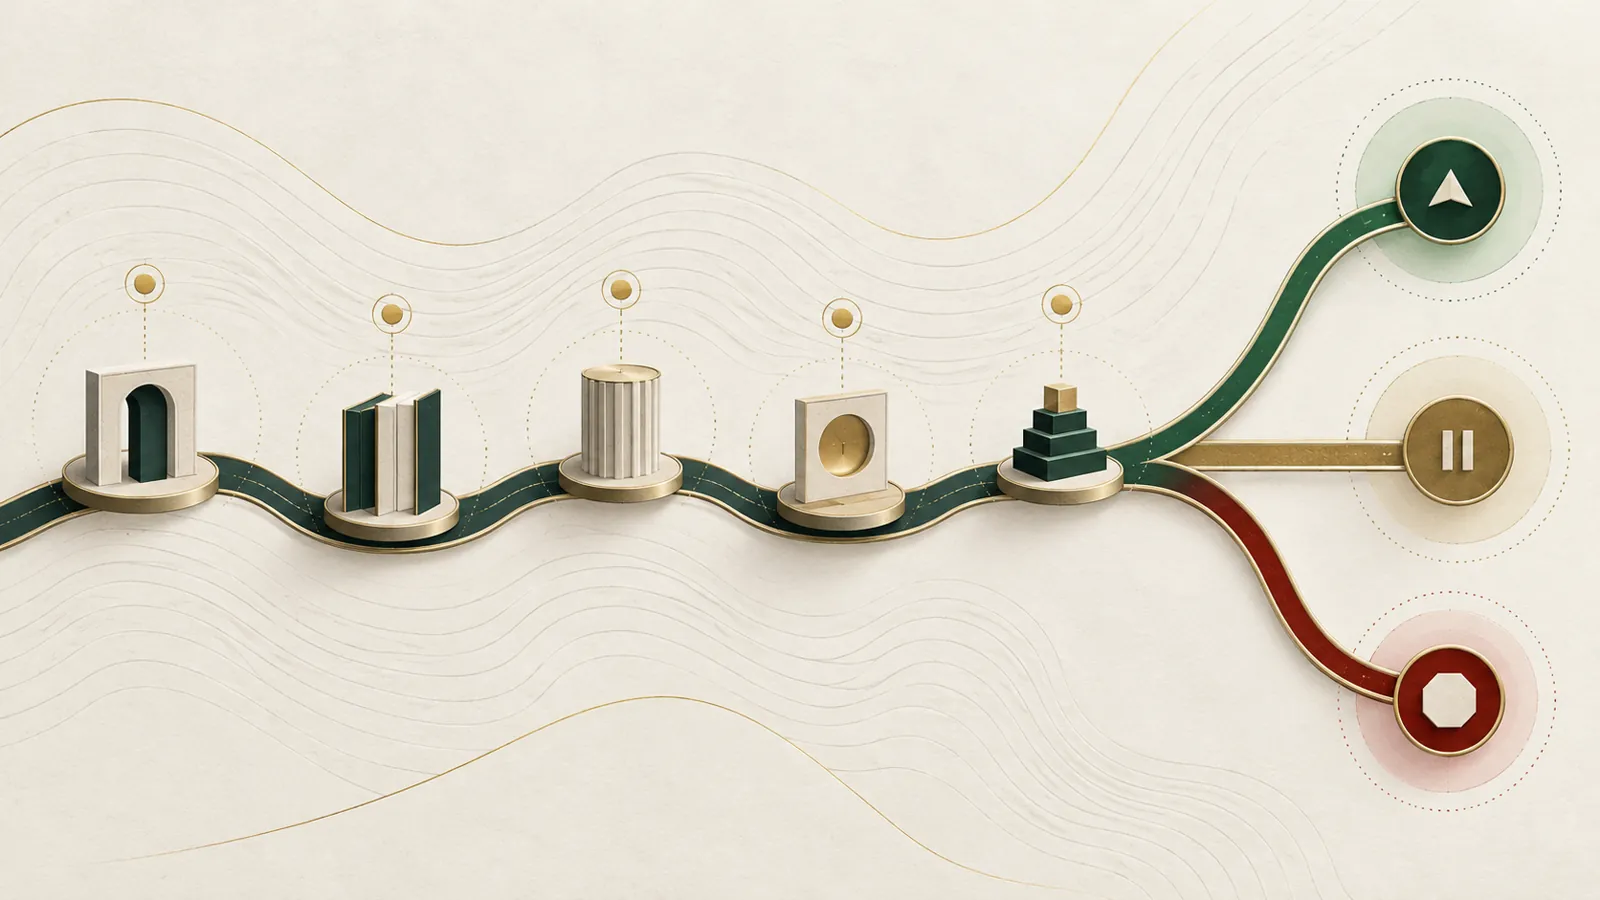
Use three states:
- Proceed to a capped pilot when the remaining uncertainty can be tested within the agreed exposure ceiling.
- Pause pending one named proof when a specific unknown blocks a safe test.
- Stop when a named condition breaches the exposure ceiling.
These rules reduce the temptation to reinterpret evidence after time or money has already been committed.
5. Refresh and decide
Refresh volatile evidence on the decision date. Record the sources and dates again, then issue the decision note. A decision based on expired evidence is not current merely because the document is recent.
What does a worked fictional example look like?
Consider Northstar Systems, a fictional B2B firm assessing entry into the fictional market of Arandia. The company has named its offer, buyer, channel, and transaction model. It has also set an exposure ceiling and decision date. The example contains no claims about a real market. It makes no outcome claim.
| Lane | Current decision note | Confidence | Consequence and next test |
|---|---|---|---|
| Country and governance | Country-level sources have been named and dated, but volatile evidence requires a decision-date refresh | Medium | Refresh before the final decision |
| Regulation and market access | The exact treatment of the offer through the proposed route remains unverified | Low | Obtain specialist verification for the named offer and route |
| Commercial demand | Buyer willingness to pay has not yet been tested through a live proposition | Low | Run a bounded demand test with the named buyer group |
| Channel and partner execution | A proposed partner exists, but delivery capability has not been proven | Low | Assign a limited task with clear ownership and acceptance conditions |
| Cash, payment, currency, and exit | The team has drafted an exposure ceiling, but the transaction path and exit trigger need confirmation | Medium | Test one bounded transaction and confirm the stop condition |
The decision logic is explicit:
- Proceed to a capped pilot only if specialist verification clears the named access question and the pilot remains within the exposure ceiling.
- Pause if that verification is missing on the decision date. The missing proof is named, so the pause has a purpose.
- Stop if the access condition or transaction structure breaches the pre-agreed ceiling.
The note does not claim that Arandia is attractive or unattractive. It shows what Northstar Systems must prove before increasing commitment.
How can you score risk without false precision?
Do not publish a universal numeric country ranking. Do not assign arbitrary probabilities. Weighting depends on the decision. A regulatory question may be decisive for one offer and minor for another. Payment exposure may dominate one transaction model but not another.
Use qualitative labels to support judgment, not replace it. For example:
- Direction: improving, stable, deteriorating, or unknown.
- Confidence: high, medium, or low, based on the quality and freshness of evidence.
- Decision consequence: proceed, pause, or stop under a named condition.
Unknown is not a low score. It is a missing proof. The next test should reduce that uncertainty or show that it cannot be reduced within the exposure ceiling.
When should the evidence be refreshed?
Set an expiry date for every material item. Some evidence can change the decision. Other evidence covers volatile conditions. Refresh both types sooner. At minimum, review volatile evidence on the decision date.
The assessment record should always show:
- the source and source date;
- the date the team last checked it;
- whether the entry is fact or inference;
- the owner of the next test;
- the expiry date;
- the person authorized to overturn the decision.
Sources for the institutional facts on this page were checked on October 14, 2026.
How does the assessment connect to market entry?
A country risk assessment defines the conditions for testing a market. It does not replace a market-entry framework or an international business strategy. Those pages address the wider choice of where to compete. They also address how to compete. The assessment keeps the immediate decision tied to evidence and exposure.
The next step should be small and reversible. A pre-agreed loss or exposure limit should bound it. A live pilot can test demand, partner execution, and the transaction path. Its job is to settle the risks that decide the entry.
This is a commercial market-entry tool. Legal, sanctions, tax, investment and credit questions, and the check of the exact offer, route and transaction, go to licensed specialists.
Frequently asked questions
Is a country risk score enough to approve market entry?
No. A country score cannot validate demand, partner quality, product fit, or the exact access conditions for an offer. Use country-level evidence in the relevant lane, then test the other lanes directly.
What indicators belong in a country risk assessment?
Use indicators that bear on the named decision. Governance evidence may include the six WGI dimensions, but the assessment also needs offer-specific access evidence, buyer evidence, partner execution evidence, and payment, currency, and exit evidence.
What should happen when evidence is missing?
Record the item as unknown, state its consequence, assign an owner, and define the next test and expiry date. Pause if the missing proof blocks a test within the exposure ceiling.
How often should a country risk assessment be updated?
Update an item when its evidence expires or conditions change. Refresh volatile evidence on the decision date. Do not rely on the document date as proof that every source is current.
Who should make the final decision?
Name the decision owner in advance. The record should also state who may overturn the choice and what new evidence would justify doing so.
Turn the assessment into a bounded test
If your team has evidence but still lacks a decision-ready test, Run the Reality Check. The market-entry pilot turns the named unknowns into a small, reversible test with an agreed exposure limit.
Written by Loïc Guyon (Tileo), operator at Go International Advisory.